MP Materials Valuation Gap Amidst Rare Earth Geopolitics
MP Materials trades at a 29.2x price-to-sales multiple, signaling significant overvaluation against intrinsic estimates while facing strategic geopolitical risks from potential Chinese acquisition moves.
MP Materials Corp (NYSE: MP) is currently trading at a premium valuation that diverges sharply from its intrinsic worth, according to data from GuruFocus. The stock price of $50.19 stands 24.8% above the estimated intrinsic value of $40.23 per share. This valuation gap persists despite the company’s ongoing unprofitability, with a trailing twelve-month EPS of -$0.35 and negative operating margins. The market is effectively pricing in substantial future growth, assigning a 29.2x price-to-sales ratio that is significantly higher than the company's historical median of 17.6x.
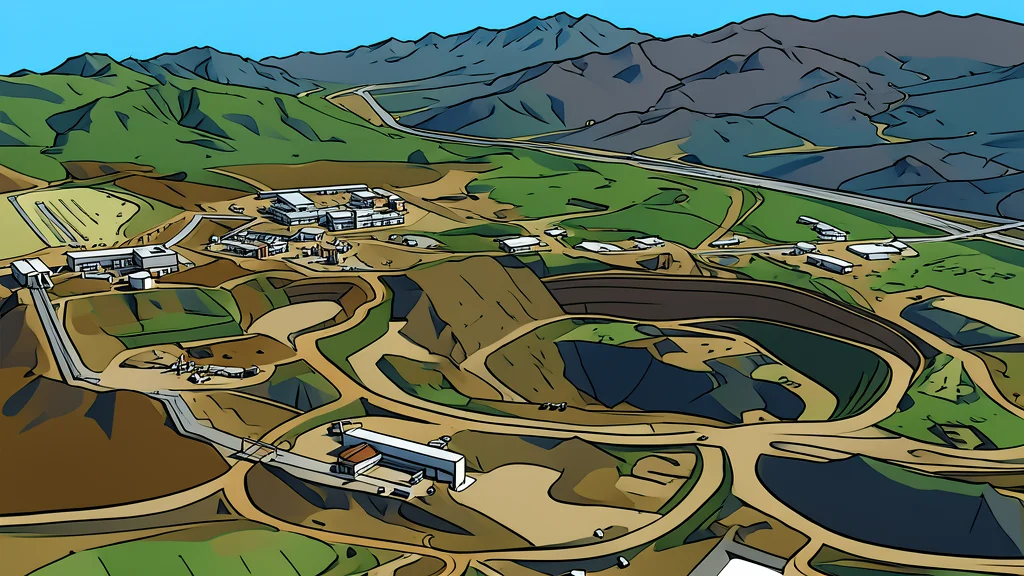
The primary catalyst for this premium is the strategic importance of MP’s Mountain Pass facility in California, the only large-scale rare earth mining and processing site in North America. However, recent reports indicate that China Rare Earth Group is negotiating to acquire Shenghe Resources, a holder of a 3% stake in MP. This move threatens to deepen Beijing’s influence over a supply chain that is critical for U.S. defense and technology sectors. The U.S. Department of Defense is MP’s largest shareholder, having committed $400 million in preferred stock and warrants, creating a complex geopolitical intersection between domestic supply security and foreign state-owned enterprise interest.
Valuation Metrics Reflect Growth Expectations
Traditional earnings-based metrics are inapplicable for MP Materials due to its current loss-making status, necessitating a reliance on price-to-sales ratios for valuation. The current 29.21x P/S ratio indicates that investors are paying for anticipated expansion in downstream capabilities, specifically the production of rare earth metals, alloys, and magnets at the company’s Fort Worth, Texas facility. This premium reflects the market’s anticipation of increased global demand for critical materials used in electric vehicles and electronics, despite the lack of current profitability.
The GF Value metric, which estimates intrinsic value based on historical multiples, suggests the stock is overvalued by nearly a quarter. This figure serves as a directional warning rather than a precise target, as historical multiples may not fully capture the dynamics of a rapidly evolving, loss-making company. The discrepancy between the market price and the calculated intrinsic value highlights the speculative nature of the current valuation, driven more by strategic scarcity and geopolitical positioning than by immediate financial performance.
Fundamental Quality and Insider Activity
MP Materials holds a GF Score of 71 out of 100, indicating moderate overall fundamental quality with mixed signals across financial health and growth. While the company is expanding its market capitalization to $8.94 billion, it faces challenges in cash flow and profitability. Insider activity over the past 12 months shows a stark imbalance, with $146.3 million in sales versus only $1.5 million in purchases. This divergence suggests that insiders are reducing their exposure while the broader market continues to bid up the price based on long-term strategic value.
Geopolitical Risks in Supply Chains
The potential acquisition of Shenghe Resources by China Rare Earth Group underscores the strategic maneuvering in the rare earth sector. Rare earth elements are essential for high-tech components, including magnets for defense applications, making MP a target of geopolitical interest. The intersection of U.S. defense interests and Chinese state-owned entity activity creates a complex landscape for MP. The company’s role as a domestic supplier is critical, but the threat of increased foreign influence through indirect ownership poses significant regulatory and strategic risks that could impact its long-term stability.
Investors must weigh the premium valuation against these geopolitical and fundamental risks. The market’s willingness to assign a high multiple to MP reflects its importance in the global supply chain, but the lack of profitability and the potential for foreign interference introduce uncertainty. The company’s ability to maintain its position as a key player in the rare earth supply chain will depend on navigating these complex dynamics while delivering on its growth promises in the downstream manufacturing sector.